(Aug. 27, 2021) Credit unions seeking certification as community development financial institutions (CDFIs) can apply for NCUA’s streamlined qualification process between Sept. 12 and Oct. 15, the agency said this week.
The CDFI certification is open only to federally insured credit unions that hold the agency’s low-income credit union designation. Those certified are eligible to apply for financial and technical assistance awards from the Treasury CDFI Fund to support their work in low-income and underserved people and communities.
To qualify for the streamlined process, low-income-designated credit unions must register in the NCUA’s CyberGrants system and complete an online participation form. The agency said its Office of Credit Union Resources and Expansion will review each credit union’s products, services, and other indicators to determine whether the credit union qualifies for the streamlined certification application.
Qualified credit unions will be given the information they need to complete and submit the streamlined certification application to the CDFI Fund, the NCUA said. The CDFI Fund will make the final certification decisions.
LINK:
Streamlined CDFI Application Qualifying Round Opens Sept. 12
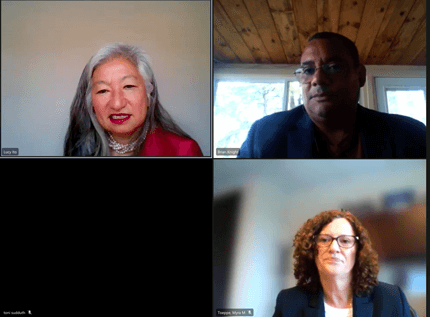
(Clockwise from upper left: NASCUS’ Lucy Ito joins NASCUS Executive Vice President and General Counsel Brian Knight, and NCUA Office of Examination and Insurance Director Myra Toeppe in a discussion of key issues)
(Aug. 20, 2021) The surging Delta variant of the coronavirus is putting a damper on NCUA’s plan to resume on-site operations, including exams, the agency’s top supervisor told the NASCUS S3 conference this week.
According to NCUA Office of Examination and Insurance Director Myra Toeppe, the continued phasing-in of on-site operations depends on the virus variant. She indicated a timetable still needs to be determined. However, the agency is ready (and willing) to go into a credit union whenever it sees a risk to the insurance fund, she said.
“We’ll go in where we need to go in if we see a risk to the insurance fund; we have been clear on that,” Toeppe said during a Tuesday session of the conference. (She was sitting in on the session in place of NCUA Board Chairman Todd Harper, who was unable to attend.) “We do have problem case officers that are doing things. Our regional offices, if we need to be on site, they will get with the (NCUA) executive director to determine from an insurance perspective if we need to go in. We’ve actually had to do some conservatorships during this time. Those are the exception, not the rule.”
But Toeppe emphasized that the agency would move with caution in any event. “People matter,” she said.
The agency’s top examiner also offered a strong defense for NCUA’s call for third-party vendor exam authority. “We do need it,” Toeppe, a former savings and loan regulator, said. “When I first came over to NCUA, I was stunned we didn’t have third-party vendor exam authority. I was used to always having it.” She said her former agency was never accused of abusing the authority, “and it was never a problem.”
Toeppe said NCUA sees reliance “more and more and more” by credit unions on the use of vendors and third parties to help them in a number of areas. She cited data processing and lending as examples.
The agency executive asserted that use of third-party vendors can become a source of risk to the share insurance fund. “And that’s always my focus,” she said. “We want to be sure we aren’t exposing the insurance fund to undue risk. And that’s really where it comes from; it’s a risk perspective for NCUA.”
She added that if the agency secures the authority (which will take an act of Congress to do so), NCUA would use it cautiously. She disputed some reports that the agency would be “ramping up” such as by hiring 500 additional examiners. “I think we’d use (the authority) prudently, where needed, just exactly like the state supervisors have done,” she said. “Where it’s needed, when it’s needed when we see a risk– just like the state supervisors, they’ve used it prudently. The banking regulators use it prudently. I don’t think there would be any difference.
She said that using the authority, when needed, is necessary to avoid a regulatory blind spot. “From (the perspective of) managing the share insurance fund, that makes us very nervous. That’s one thing that keeps me up at night,” she said.
In other comments, Toeppe said:
- Cybersecurity is a persistent threat; the one risk that just doesn’t go away. “We have ebbs and flows of other risks, but cybersecurity just keeps coming,” she said. “It just doesn’t stop, it’s in everything. It’s the constant ‘come at you’ thing. It’s high level, persistent.”
- NCUA is not discouraging mergers among credit unions (as opposed to banking regulators with banks, under an executive order from President Joe Biden). “We don’t tell (credit unions) no you can’t merge, but we want to make sure they are doing the right thing.”
- She has no problem with credit unions buying banks, as long as the transaction is done well and the credit union has done its homework. “Everyone thinks we rubber stamp them,” she said, adding the agency does not. She said the transaction must make sense, and that the agency has be sure of the risk that the insurance fund is taking on with the transaction.
(Aug. 20, 2021) A proposal by NCUA to create the new “complex credit union leverage ratio (CCULR)” framework — the credit union equivalent of the community bank leverage ratio (CBLR) — is out for public comment until Oct. 15, according to a notice published in the Federal Register this week. Issued for comment during the July 22 NCUA Board meeting, the proposed rule would make a simplified measure of capital adequacy available to federally insured credit unions defined as “complex” – meaning those with more than $500 million in assets … The spread of the Delta variant of the coronavirus and stagnant vaccination rates pose “downside risks” to the economic outlook, according to members of the Fed’s rate-setting Federal Open Market Committee, as expressed in the minutes of the meeting from July 27-28. The minutes were released this week. Committee members also noted economic uncertainty remains high and that supply disruptions and labor shortages might last for longer than anticipated … NCUA is scheduling a Sept. 8 webinar on its modernized examination tools. The session, which gets underway at 2 p.m. ET and runs for an hour, will focus on the new modern examination platforms and systems, including the agency’s Modern Examination & Risk Identification Tool, (MERIT), as well as associated programs: the Data Exchange Application (DEXA), NCUA Connect, and the Admin Portal. The agency said registration is now open.
LINKS:
Capital Adequacy: The Complex Credit Union Leverage Ratio; Risk-Based Capital
Minutes of the Federal Open Market Committee, July 27-28, 2021
Register Now for NCUA’s Modernized Examination Tools Webinar on Sept. 8
(Aug. 20, 2021) Reorganizing its rules to lessen confusion over application of anti-money laundering rules, and working with state regulators to implement those rules, are among the recommendations made by NASCUS in its letter to NCUA concerning the latest annual review of the agency’s regulations.
In February, NCUA asked for comments on its annual review of agency rules, which covers one-third of the regulations (the review is conducted over a three-year period to ensure all agency rules are reviewed at least once every three years). Among the rules being reviewed in 2021: Security program, report of suspected crimes, suspicious transactions, catastrophic acts and Bank Secrecy Act compliance (Part 748 of the agency’s rules), among other things.
The state system offered comments in several areas, including BSA/AML compliance, reporting of suspicious transactions, and organization of NCUA rules (particularly those affecting state credit unions).
Regarding anti-money laundering rules, NASCUS noted that Treasury’s Financial Crimes Enforcement Network (FinCEN) is proceeding with a “no-action letter” program for BSA/AML rules over which that agency has enforcement authority. The program will not affect NCUA rules, NASCUS noted. To mitigate confusion, NASCUS recommended that NCUA rules be reorganized to co-locate or otherwise more clearly identify BSA/AML “FinCEN” rules and NCUA specific rules.
NASCUS also urged NCUA to revisit the monthly requirement that credit union boards be informed of suspicious activity reports (SARs) required under BSA/AML. While that may work for federal credit unions (which are required to meet monthly), NASCUS noted, it does not work for state credit unions where boards are only required to meet quarterly. “In other covered industries, including banking, best practice for reporting to the entity’s board is quarterly, or synchronized to regularly scheduled board meetings,” NASCUS wrote. “NCUA should clarify its expectations for how reporting is handled and make clear that for credit unions with less-than-monthly board meeting, reporting SAR filings at the next available board meeting, or quarterly, would satisfy the regulatory requirement.”
In other comments, NASCUS:
- Reiterated the importance of NCUA working with state regulators to develop regulations to implement the Anti-Money Laundering/Countering the Financing of Terrorism (AML/CFT) National Priorities (National Priorities) as published by the Treasury Department on June 30. NASCUS recommended the agency create a working group with state regulators to develop pending regulations.
- Recommended the agency reinstate the policy of publishing a summary and response to stakeholder comments. “There is real value for stakeholders in understanding NCUA’s response to recommended changes and in gaining insight into the agency’s rational for resisting making various recommended changes,” NASCUS wrote.
- Repeated its call that NCUA reorganize its rules to consolidate and co-locate all National Credit Union Share Insurance Fund (NCUSIF) rules for federally insured credit unions (FISCUs) in one section (or series of consecutive sections), which NASCUS asserted would “provide significant regulatory relief to credit unions without increasing risk to the NCUSIF.”
- Proposed the agency develop a regular review of guidance as a companion to the annual regulatory review. “While not carrying the force of regulation or statute, supervisory guidance provides stakeholders crucial insight into how NCUA interprets compliance with regulation, and as such is just as critical to be regularly evaluated.,” NASCUS wrote.
- Observed that agency rules could be made more consistent by ensuring regulatory provisions containing mandatory elements of compliance contain mandatory language rather than permissive language. “Requirements should also be stated in the active tense such as ‘a credit union shall design its information security program’ rather than passive construction such as a ‘credit union information security program should be designed,’” NASCUS stated.
LINK:
NASCUS comment letter: 2021 NCUA regulatory review
(Aug. 20, 2021) Summaries of three recent issuances from NCUA – on capitalizing loans, the rollout of the new examination tool, and on mortgage servicing rules – were published by NASCUS this week.
All three are available to members only. The summaries cover issuances – two letters to credit unions and one regulatory alert – issued by the agency over the last three weeks or so.
Early this month, the agency issued letter to credit unions (LTCU) 21-CU-07, which outlined limits on capitalization of loans to members. In particular, the letter pointed out, the financing of fees and commissions continue to be prohibited for federally insured credit unions, despite adoption of the new rule earlier this year allowing capitalization of loan interest. In the letter, the agency said that maintaining the prohibition on capitalization of fees “is an important consumer protection feature of the rule for member borrowers.”
In June, the agency’s board voted unanimously to lift the prohibition of capitalization of interest in connection with loan workouts and modifications; the rule took effect July 30. The change was made, NCUA said, to give borrowers additional access to loan workouts, perhaps caused by the economic disruption caused by the coronavirus crisis.
The second letter (LTCU 21-CU-08) summarized listed the new applications (and their implementation) the agency is employing for assisting in exams and communicating to credit unions. The letter, issued just last week, noted that the agency would begin transitioning to its new Modern Examination and Risk Identification Tool (MERIT) exam tool and other applications meant to modernize and streamline the agency’s operations. The other tools include the Data Exchange Application (DEXA), the Administrative Portal, and the Consumer Access Process and Reporting Information System (CAPRIS) for federal credit unions.
The letter also offers insights about who at credit unions can use the new tools, and how the tools integrate with state supervisory authority (SSA) examination and supervision programs.
The third item summarized by NASCUS and published this week is of a regulatory alert (21-RA-08), which urges review of CFPB mortgage servicing rules. According to the alert, credit unions are urged to review the June 30 rule temporarily amending certain mortgage servicing requirements under the bureau’s Regulation X to assist borrowers affected by the COVID-19 emergency. The alert noted that the CFPB rule — which takes effect Aug. 31 — only applies to servicers that service mortgages secured by a borrower’s principal residence and does not apply to small servicers.
LINKS:
NASCUS summary: LTCU 21-CU-07, Capitalization of Unpaid Interest (members only)
NASCUS summary: LTCU 21-CU-08, Implementation of Modernized Systems (members only)
NASCUS summary: 21-RA-07 Equal Credit Opportunity Act (Regulation B) (members only)
(Aug. 13, 2021) NCUA this month will begin transitioning to the new MERIT exam tool and other applications meant to modernize and streamline the agency’s operations, according to a letter to federally insured credit unions issued Thursday.
NCUA’s Letter to Credit Unions (LTCU) 21-CU-08 states that the new applications may be accessed through NCUA Connect, another of its applications debuting this month, which the agency described as a central user interface which credit unions use to securely interact with the agency.
In addition to MERIT (the Modern Examination and Risk Identification Tool) the applications include:
- Data Exchange Application (DEXA): an “ingest tool” that provides authorized NCUA, state supervisory authority (SSA), and credit union users the ability to securely upload the credit union member loan and share data requested during the examination and supervision process.
- Admin Portal: designed to provide authorized credit union administrative users with the ability to manage user access to NCUA Connect and other applications for their credit unions.
- Consumer Access Process and Reporting Information System (CAPRIS, which replaces the Field of Membership Internet Application (FOMIA): for use by multiple common bond FCUs to submit field of membership expansion requests electronically.
Credit unions that want to use the applications, the letter notes, must identify two individuals as admin portal administrators with delegated responsibility for managing the users for their credit union. “Once approved and confirmed by the NCUA, administrators can add users and grant application access,” the agency stated. “As part of the process, the administrator will be granted access to NCUA Connect to access the Admin Portal application.”
The agency also noted that MERIT – which is designed to provide examiners with visualizations to identify trends and potential risks in credit unions through enhanced, integrated analytics – allows SSAs and NCUA to work jointly on examinations, “reducing redundancy, increasing efficiency, and improving communication.”
(NASCUS developed a team of state regulators to offer feedback to the agency as the system was developed; NASCUS will continue to consult with the agency as the system is deployed).
According to NCUA, MERIT gives examiners the ability to document examination results, generate the report issued to the credit union, and formally follow up on examination concerns. The agency said the new system allows credit unions to securely transfer documents to their NCUA and SSA exam teams (as applicable) through the system’s “survey” functionality. “Examiners can send a document request list (survey) through MERIT rather than through other manual or electronic means, thus improving the efficiency of the document request process,” NCUA said.
Before credit unions request to obtain access to information from MERIT (or DEXA), NCUA said credit unions should wait until they are notified of their first exam in MERIT. Doing so before that, NCUA suggested, would be fruitless since there is no information specific to credit unions in the system until the first MERIT exam. “Further, as part of enhanced security, user accounts are locked after a period of inactivity, and user access would need to be restored once notified of an upcoming examination,” the agency said.
The LTCU also lists user training opportunities for the new systems, complete with Internet links.
LINK:
NCUA LTCU 21-CU-08: Implementation of Modernized Systems
(Aug. 13, 2021) Todd Harper could remain chairman of the NCUA Board through at least 2024, and would be able to stay on the agency board (either as board leader or a member) until at least April 2027, if the Senate confirms him to another term as recommended by the White House this week.
On Tuesday, President Joe Biden (D) sent Harper’s nomination to continue to be a member of the NCUA Board to the Senate. The White House release noted the action is a “reappointment” to the agency board, and would be for a term expiring April 10, 2027.
Harper joined the board after confirmation by the Senate in March 2019, following his nomination to the seat by President Donald Trump (R) in February. He was named chairman of the board, succeeding Republican appointee Rodney Hood, in January of this year by the newly inaugurated Biden.
If confirmed, Harper may continue to be chairman of the three-member board. However, should Biden serve only one term (by not prevailing in the 2024 election, for instance), the next president could designate another board member as chairman. In any event, the chairman serves at the pleasure of the president, whoever that may be.
Since joining the board, Harper was filling a term that was held by former NCUA Board Chairman Debbie Matz and that began in 2015. Matz resigned in 2016, and the seat had been open until Harper filled it two years ago.
However, that six-year term officially ended in April and Harper has been serving in a holdover capacity since then (which he can do until his successor is confirmed by the Senate). In this case, Harper will be his own successor. Typically, NCUA Board members cannot succeed themselves – but there are exception and different interpretations of the exceptions. The Biden White House has essentially established a precedent in interpreting the Federal Credit Union Act to allow someone appointed to fill an unexpired term to be reappointed for a full six-year term.
Harper was the first NCUA staffer to become an agency board member and chairman. He had previously served as head of the agency’s Office of Public and Congressional Affairs and was the chief policy advisor to two former agency board chairmen, including Matz as well as Rick Metsger. He previously served in the U.S. House of Representatives as staff director for the on capital markets, insurance, and government-sponsored enterprises subcommittee and as legislative director and senior legislative assistant to former Rep. Paul Kanjorski (D-Pa.).
The nomination will head for consideration to the Senate Banking Committee, whose chairman (Sherrod Brown, D-Ohio) issued a statement this week saying he looks “forward to considering Chairman Harper’s renomination in the Committee and looks forward to continuing to work together to strengthen the NCUA and ensure credit unions can serve their members.”
No confirmation hearing date has yet been set by the Senate panel.
LINK:
White House nominations sent to the Senate
(Aug. 13, 2021) The renomination of Harper to a seat on the NCUA Board holds some other significance. First, it would keep him on the board much longer than the other two current members of the board. Second, the NCUA Board seat is only one of five federal financial institution regulators that are currently open (or filled with “acting” or holdover incumbents) for which the White House has seen fit to recently submit a nomination.
If confirmed to a new term, NCUA Board Chairman Todd Harper would immediately snare the longest tenure of the three current members of the NCUA Board. Now-Member (and former chairman) Hood’s term ends two years from now (in August 2023). The term of Vice Chairman Kyle Hauptman (also a Republican nominee) ends in August 2025.
By naming Harper to a new term, the Biden administration is attempting to fill permanently (that is, not in an acting or holdover capacity) one of five empty or expired financial regulators’ terms. Four of those are still seeking a nominee to fill the seat permanently. Those are:
- Comptroller of the Currency (now filled by Acting Comptroller Michael J. Hsu);
- Vice chairman of the FDIC Board (now vacant);
- Member of the Federal Reserve Board (now vacant);
- Member of the FDIC Board (now held by Martin Gruenberg, serving in a holdover capacity since December 2018).
No one has been nominated to permanently fill any of those vacant, acting, or holdover positions.
A sixth position, for a permanent director of the Consumer Financial Protection Bureau (CFPB), has a nominee – Rohit Chopra, now a member of the Federal Trade Commission (FTC). Chopra’s nomination was recommended to the full Senate by tied vote (12-12) in March. The nomination, for a five-year term, now awaits action by the Senate; no vote has yet been scheduled. In the meantime, Dave Uejio has been filling the seat – but his days at the helm of the bureau may be numbered. On Aug. 5, Uejio appeared before the Senate Banking Committee for a confirmation hearing on his nomination to be assistant secretary of Housing and Urban Development (HUD).
(Aug. 6, 2021) Miguel A. Polanco, a former Army officer and investment banker, is now the top workforce and supplier diversity officer NCUA, the agency announced this week. The agency said Polanco will serve as director of the agency’s Office of Minority and Women Inclusion (OMWI); he most recently served as deputy director. He replaces Millie Avalos, who was serving as acting director.
Polanco’s other roles at the credit union regulator included managing the agency’s supplier diversity program. He also worked for the Small Business Administration (SBA) and its 8(a) program (a business assistance program for small, disadvantaged businesses). Prior to that, he worked in investment banking at Citibank Puerto Rico, and served as U.S. Army intelligence officer, NCUA said.
He is a graduate of the U.S. Military Academy at West Point and the Kellogg Graduate School of Management at Northwestern University.
LINK:
Polanco Named NCUA Director for the Office of Minority and Women Inclusion
(Aug. 6, 2021) The financing of fees and commissions continue to be prohibited for federally insured credit unions, despite adoption of a new rule earlier this year allowing capitalization of loan interest, NCUA said in a letter issued Thursday.
In Letter to Credit Unions 21-CU-07, the agency said that maintaining the prohibition on capitalization of fees “is an important consumer protection feature of the rule for member borrowers.”
In June, the agency’s board voted unanimously to lift the prohibition of capitalization of interest in connection with loan workouts and modifications; the rule took effect late last week (July 30). The change was made, NCUA said, to give borrowers additional access to loan workouts, perhaps caused by the economic disruption caused by the coronavirus crisis.
The rule also sets documentation requirements to help ensure that the addition of unpaid interest to the principal balance of a mortgage loan does not hinder the borrower’s ability to become current on the loan.
Although the final rule prohibits capitalizing loan fees and commissions, the letter notes it does continue to allow advances to cover third-party fees to protect loan collateral, such as for force-placed insurance or property taxes.
The letter also suggests that “a prudently underwritten and appropriately managed loan modification, consistent with safe and sound lending practices” is the best approach for helping borrowers.
Other key points of the letter include:
- All documentation for loan capitalizations, including required disclosures, must be accurate, clear and conspicuous, “and consistent with applicable federal and state laws and regulations.” The agency said any adverse credit reporting must be accurate and comply with the requirements of the Fair Credit Reporting Act, and, when applicable, state law.
- Credit unions should document why capitalizing interest is the best course of action when determining the terms of the modification. “Further, the rule requires the credit union’s policy ensure that a credit union makes loan workout decisions based on a borrower’s renewed willingness and ability to repay the loan,” the letter states.
- A credit union’s policy must also establish limits on the number of modifications permitted for an individual loan. “If a credit union restructures an individual loan more than once a year or twice in five years, examiners will expect the documentation to reflect the borrower’s continued willingness and ability to repay the loan,” the letter states.
NASCUS wrote in its comment letter on the proposal earlier this year, that it had the capacity to provide credit unions with greater flexibility to work with economically distressed members (including those affected by the coronavirus crisis). “That enhanced flexibility benefits distressed credit union borrowers by expanding the options for repayment programs as the member regains their economic footing,” NASCUS wrote.
LINK:
NCUA Letter to Credit Unions 21-CU-07: Capitalization of Unpaid Interest
(Aug. 6, 2021) Congress should give NCUA authority to examine (and enforce actions) over third party vendors, NCUA Board Chairman Todd Harper said in testimony to the Senate Banking Committee this week. He also urged Congress to make several improvements to the National Credit Union Share Insurance Fund (NCUSIF).
In May, Harper made similar requests before the House Financial Services Committee.
On exam authority, Harper asked Congress to give his agency exam and enforcement oversight of third-party vendors, including credit union service organizations (CUSOs). Calling the lack of authority a “regulatory blind spot,” Harper asserted that NCUA should have comparable authority as other federal financial institution regulators already have.
“While there are many advantages to using these service providers, the concentration of credit union services within CUSOs and third-party vendors presents safety and soundness and compliance risk for the credit union industry,” Harper told the committee.
He said the top five credit union core processor vendors provide services to approximately 87% of total assets held by credit unions. Additionally, he said, the top five CUSOs provide services to nearly 96% of total credit union system assets.
“A failure of even one of these vendors represents a significant potential risk to the (National Credit Union) Share Insurance Fund and the potential for losses from these organizations are not hypothetical,” Harper asserted. “Between 2008 and 2015, CUSOs contributed to more than $300 million in losses to the Share Insurance Fund alone.”
The NCUA Board chairman told the committee that the continued transfer of operations from credit unions to CUSOs and other third parties diminished the agency’s ability to “accurately assess all the risks present in the credit union system and determine if current CUSO or third-party vendor risk-mitigation strategies are adequate.”
NASCUS supports the agency obtaining the power over technology service providers (TSPs) that provide services to federally insured credit unions — provided that any such authority requires NCUA to rely on state examinations of such service providers where such authority exists at the state level. Further, NASCUS supports efforts to strengthen state regulatory exam and supervision of third parties providing services to state-chartered credit unions.
Regarding the insurance fund, Harper made three legislative requests to the committee:
- Increase the fund’s capacity by removing the 1.50% statutory ceiling on its capitalization;
- Remove the limitation on assessing premiums when the equity ratio exceeds 1.30% of equity in the fund to insured shares, giving the NCUA Board discretion on the assessment of premiums;
- Institute a risk-based premium system.
LINK:
(Aug. 6, 2021) The Massachusetts Division of Banks is looking for candidates to fill the position of chief director of risk management (safety & soundness) supervision. For more information, see the NASCUS Career/Job Postings page (link below) … Federal credit unions were advised by NCUA this week that the 18% loan ceiling was continued by the agency, following board action in June. The 18% ceiling runs for 18 months, expiring March 10, 2023. The current 18% loan rate ceiling for FCUs ends Sept. 10.
LINKS:
NCUA Letter to FCUs 21-FCU-04: Permissible Loan Interest Rate Ceiling Extended